The UPI PIN, and paying when there is no internet
Two of the three most searched things about UPI are the same thing: setting a PIN and resetting it. Both come down to one object you already have.
18+ only. This site is not NPCI, not a bank and not a casino.
The debit card is the key to the whole thing
Not an OTP from support, not a call centre. The card details are what the system asks for, the first time and every later time.
- Register with a provider and link the account
Registration comes before anything else. If the account will not appear, the usual cause is the mobile number: it has to be the one already sitting on the bank account.
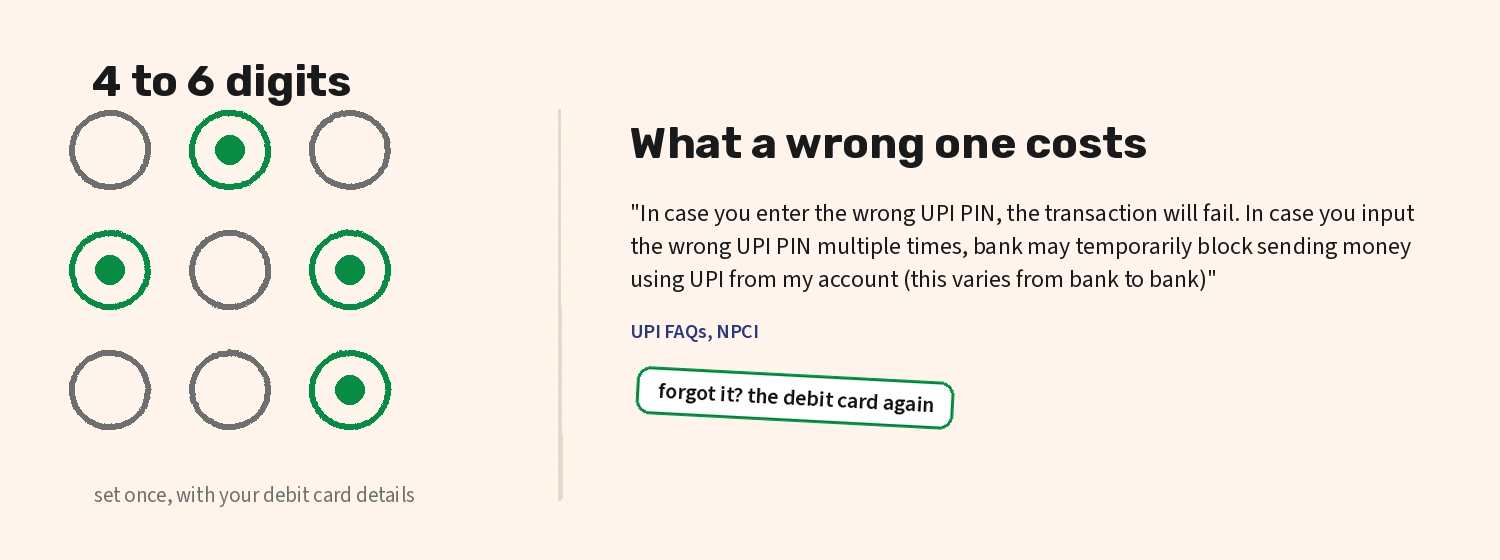
- Set the code using the debit card details
NPCI: «You can set your UPI pin on any PSP app using your debit card details.» The same route is what regenerates it if you forget it later.
- Use it for every authorisation
There is no threshold under which it is skipped and no auto-deduction: their page says plainly that payments are not deducted from the account on their own.
- Know what a wrong one does
The payment fails. Repeat it several times and the bank may temporarily block sending money over UPI from that account, and how many attempts that takes «varies from bank to bank».
What the shop is on the other end of
The buyer sees one screen. Behind it the shop has a bank, a set of integration modes and a settlement that happens immediately.
- The shop has to be signed up with an acquiring bank
NPCI: «merchant need to partner with the acquirer bank. Acquiring bank will provide the UPI infrastructure to merchant.» A shop cannot switch it on alone.
- Money reaches them at once
Their page: the merchant receives the money immediately after the customer confirms, into the merchant pool account or the merchant’s own account.
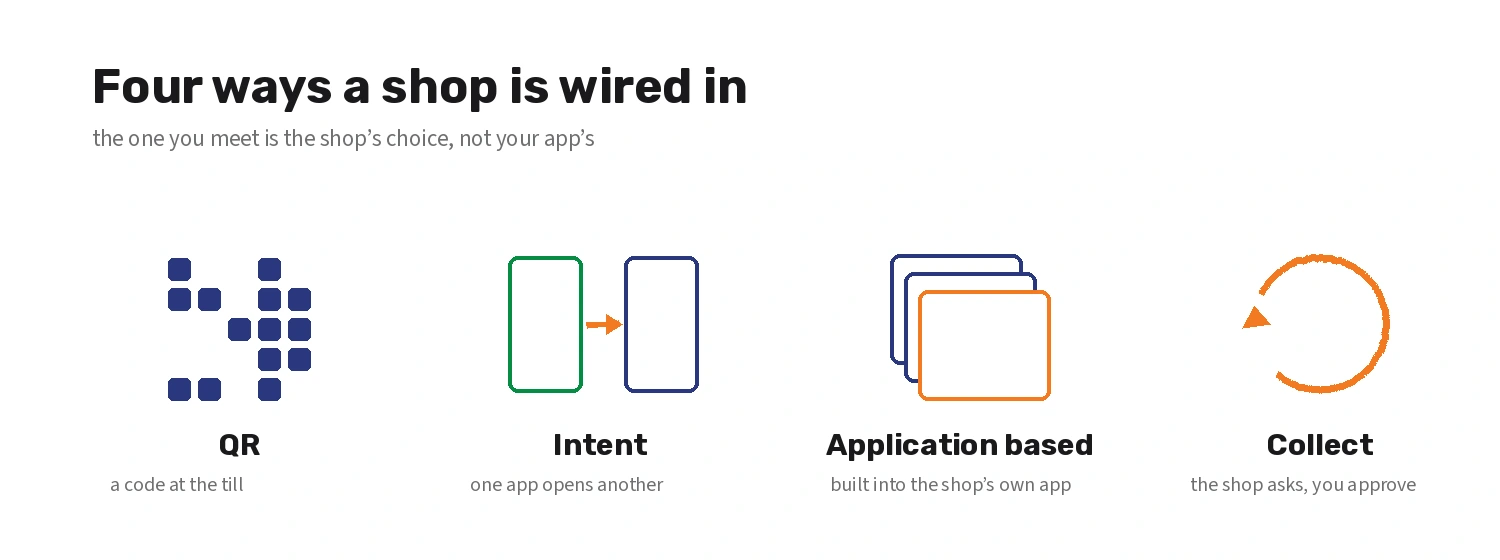
- There are four ways it can be wired in
QR, intent, application based and collect. Which one you meet depends on the shop, not on your app.
- A four digit code describes the shop
The merchant category code, «four digit number listed in the ISO 18245 for retail financial services». It is the thing category-based rules are applied against.
One more asymmetry worth carrying around: a collect request has no fixed expiry written into the system. NPCI answers the question about how long a payer has to approve one with a single sentence — the timeline «needs to be defined by the requester».
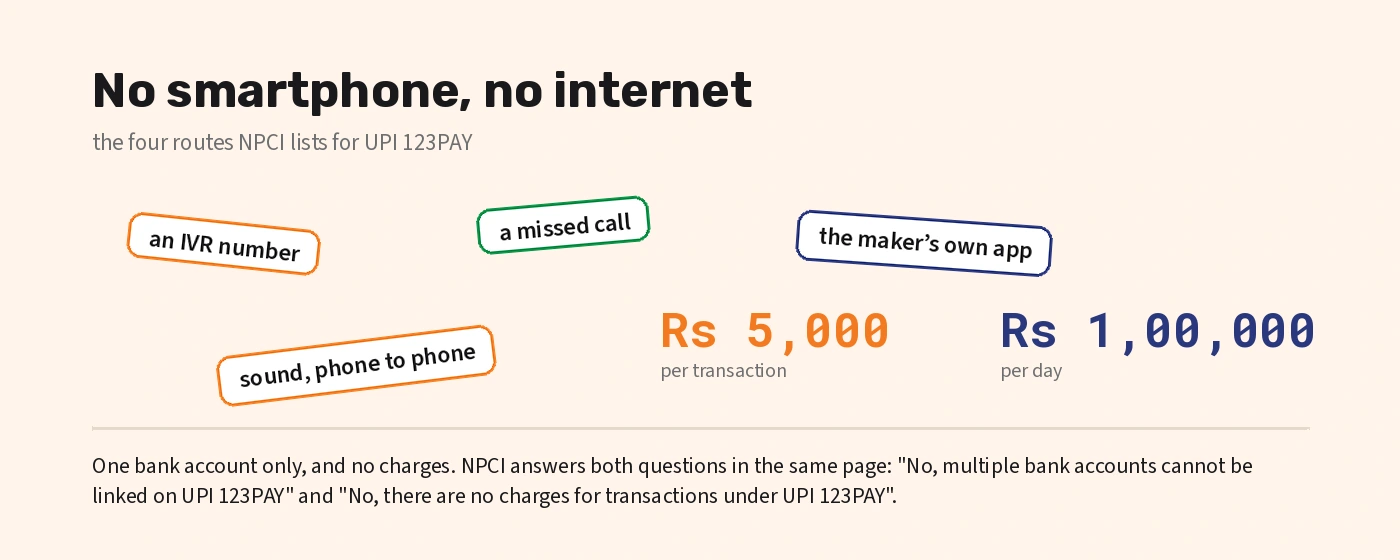
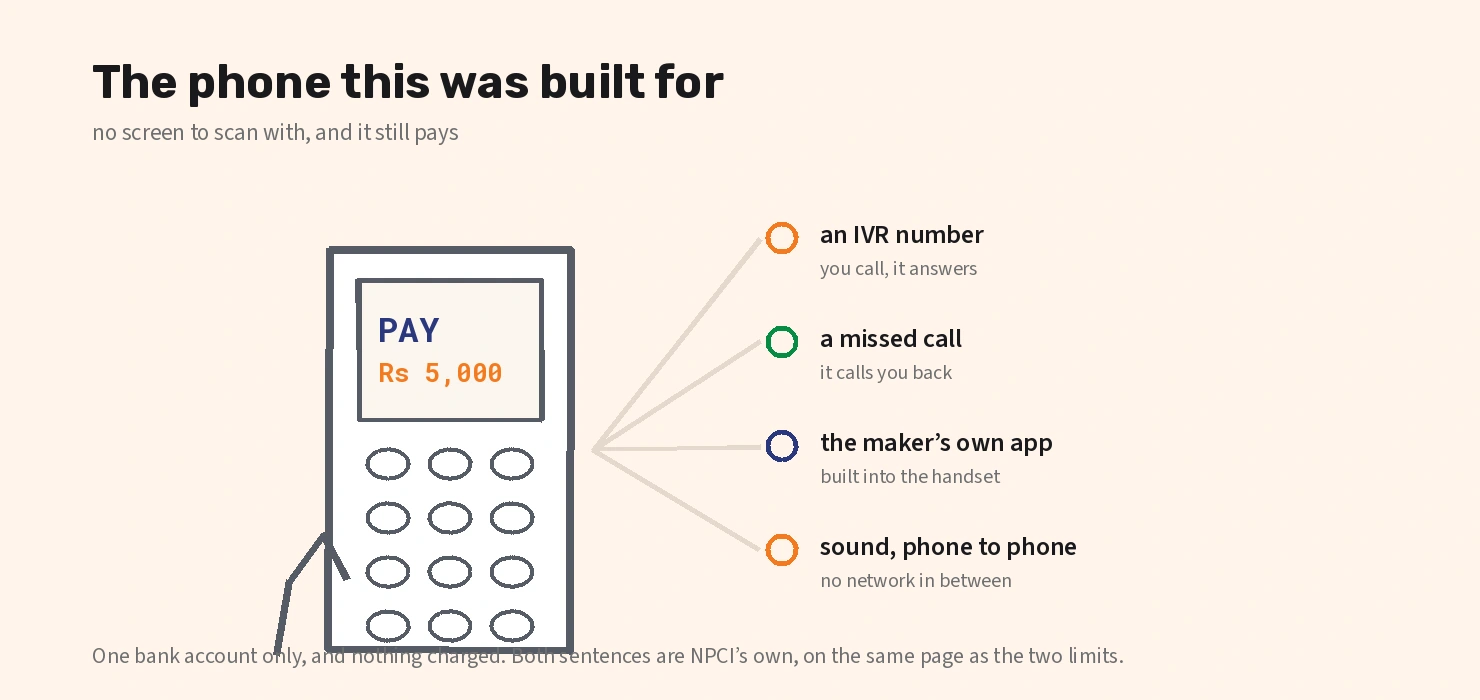
Four routes that do not need a data connection
This is the one corner of UPI where NPCI publishes a daily rupee figure, and it is the corner most articles skip.
What you give up in exchange
One bank account, and one only: multiple accounts cannot be linked on 123PAY. In return the price is the same as everywhere else on UPI, which is nothing.
Under five hundred, the handset carries it
A separate product with a narrow job, and a detail about leaving it that is easy to miss.
«UPI LITE is a new payment solution that leverages the trusted NPCI Common Library (CL) application to process low value transactions» — the threshold NPCI names is below Rs 500.
UPI LITE, NPCI · read 17 September 2026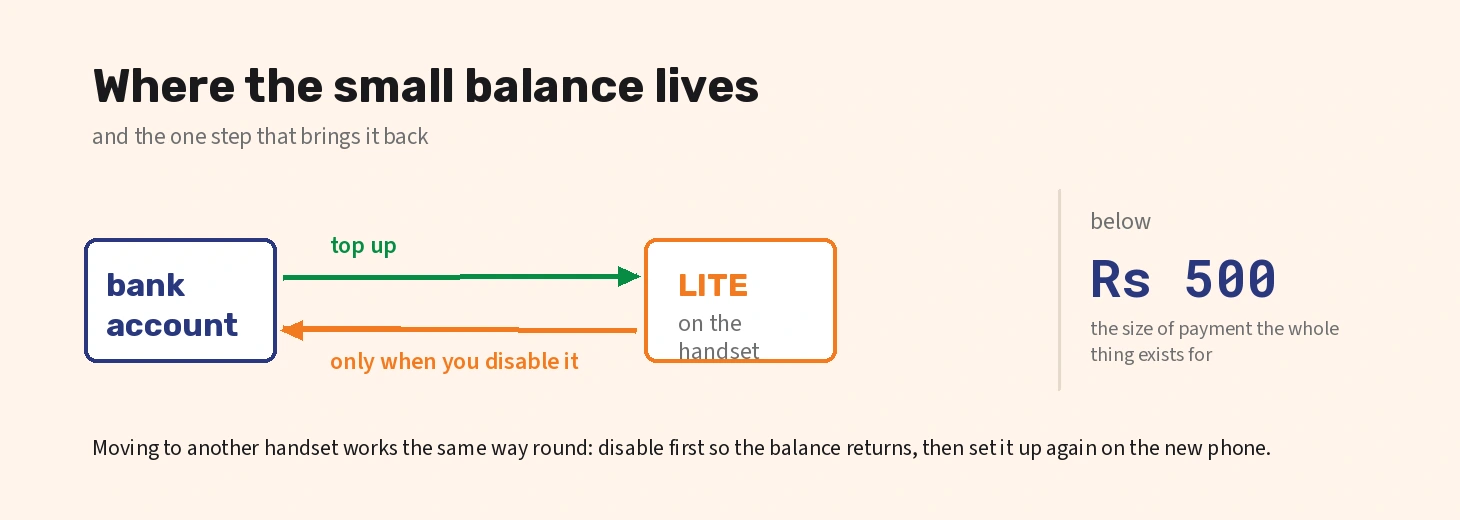
The point of it is that a small payment does not have to reach the remitting bank’s core systems in real time, which is what NPCI means when the same page talks about keeping the risk contained. The part that matters when you stop using it: the money sitting in the LITE balance comes back only when you disable the account. Moving to a new handset works the same way round — disable first so the balance returns, then set it up again on the new device. Skip that order and the balance stays where the old phone left it.
Worth checking before a first deposit
Two of these are about UPI itself and two are about whoever you are paying. They are the ones a cashier screen will not mention.
-
01
That you are the one entering the PIN
Nobody needs your UPI PIN to send you money. A request to type it in order to receive something is the request itself going wrong.
-
02
That the phone is yours and stays yours
A SIM change, a handset change or a new app all force a fresh registration, and the address you had may not come back.
-
03
The minimum the operator itself asks for
Every casino publishes its own floor in its own cashier. That number overrides anything written anywhere else.
-
04
Which way the money comes back
The return path is decided by the operator and does not have to be the one the deposit came in on.
The links in this section are sponsored. No operator is named here because cashier rules change without notice: the list that counts is the one inside the casino itself.
What gets asked while setting this up
How many digits is a UPI PIN?
Four to six. NPCI defines it as a pass code you create during first time registration in the app, and it is separate from the code your bank uses for other things.
How do I set the PIN in the first place?
With your debit card details, in whichever provider app you registered with. Their wording is that you can set it on any PSP app using those details.
I have forgotten mine. What now?
The same route again: regenerate a new one using the debit card details. There is no separate reset channel described anywhere on the published pages.
What happens if I keep entering it wrong?
The payment fails each time, and after several attempts the bank may temporarily block sending money over UPI from that account. How many attempts that takes varies from one bank to another.
My bank account will not show up when I link it. Why?
The usual cause is the mobile number. It has to be the same number that is already registered against the bank account.
Can I pay without a smartphone or without internet?
Yes, through UPI 123PAY. NPCI lists four routes: an IVR number, a missed call, functionality built by the handset maker, and sound-based payments.
What are the limits on a feature phone?
Rs 5,000 for one payment and Rs 1,00,000 in a day, with no charges. Only one bank account can be linked on 123PAY.
What is UPI LITE meant for?
Low value payments, below Rs 500, handled on the device without reaching the remitting bank’s core systems in real time. Disable it to get the remaining balance back into the account.
Will anything be deducted from my account automatically?
Not on its own. NPCI states that payments are not auto-deducted, and every authorisation goes through the PIN.